
Qualcomm reported disappointing quarterly results and guidance, sending shares lower. Shares are down roughly 40% since peaking in late May and now yield 2.4%.
Revenue of $9.95 billion for the fiscal third quarter declined 4%. The Qualcomm CDMA Technologies (QCT) segment declined 5%, led by a 20% drop in Handsets that was offset by a 61% jump in Automotive and 9% increase in Internet of Things (IoT).
The Handset decline reflects the impact of the industry-wide memory shortage in the global smartphone market, including weakness from Chinese OEMs.
Qualcomm Technology Licensing (QTL) declined by 3%, in line with expectations.
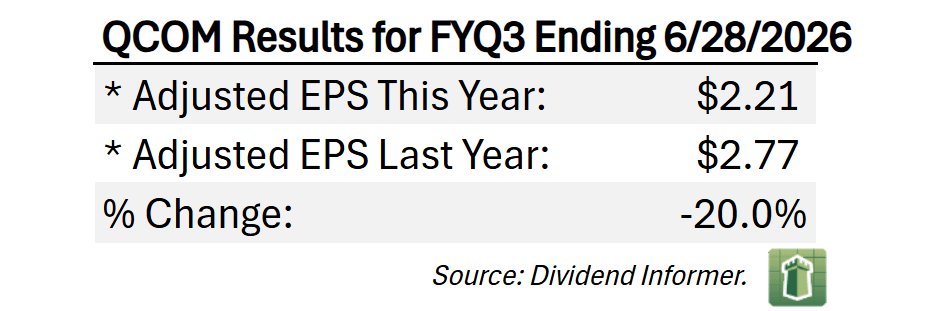
Adjusted EPS of $2.21 dropped 20% due to lower revenue, a decrease in gross margin from higher component costs, and increased operating expenses to support research and development for the firm’s data center initiatives.
Fourth quarter guidance was weaker than expected, with revenue of $9.7-$10.5 billion down 7%-14% and adjusted EPS of $2.05-$2.25 down 25%-32%. The revenue decline is mainly focused on Handsets as Apple product revenues are expected to step down faster than anticipated in the quarter.
The earnings decline is due to higher semiconductor input costs and lower margin contribution from custom data center semiconductor contracts with two hyperscalers that will begin contributing revenue during the quarter.